|
|






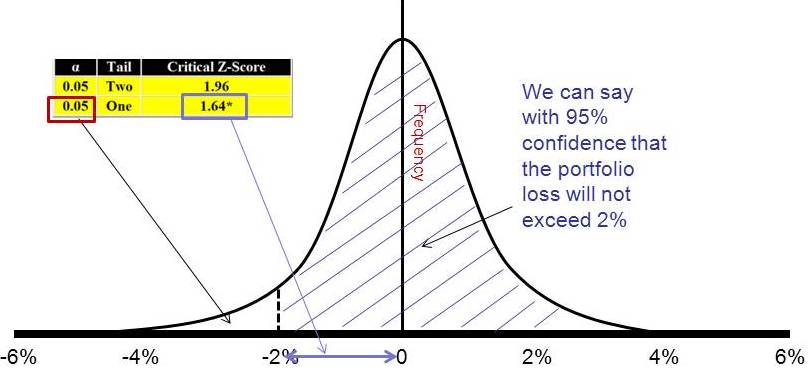
What is Value at Risk? - Adam Wong Value at Risk of a portfolio is defined as the maximum loss on a portfolio occurring within a given length of time with a given small probability. An example is shown below: |
Example VaR of the portfolio is defined as the loss (-2%) which has precisely 5% of the probability mass to its left – e.g. loss of $2m based on portfolio of $100m |